HDB Interior Design Singapore: Using a Reno Loan
HDB interior design Singapore homeowners frequently fund reno with a renovation loan, and the math is clearer than people expect. Market ranges put a 4-room BTO at about S$30,000 to S$45,000, while a resale 4-room runs S$50,000 to S$70,000 because of more hacking and rewiring. A loan bridges the gap between savings and handover.
Know the market cost before you borrow
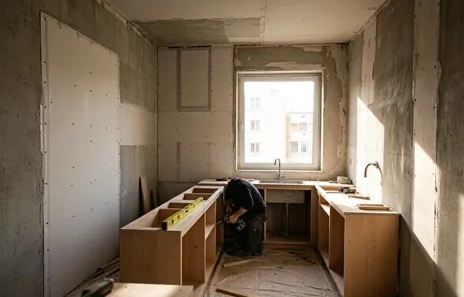
Set the loan size against the real scope, not a round number. A 3-room flat of about 60 to 65 sqm needs less carpentry than a 5-room of about 110 sqm. The resale premium comes from tearing out old works: hacked tiles, rewired circuits, and replaced pipes. Write the quote line by line so the borrowed amount matches the job.
Renovation loans from banks cap at six times your monthly income, up to S$30,000, under MAS rules. That ceiling fits a BTO scope but may not cover a full resale overhaul on its own. Pair the loan with your CPF Ordinary Account or cash for the balance. Your contractor does not set the loan, the bank does, so compare tenures and rates first.
Step-by-step loan process
The sequence keeps your BTO renovation timeline intact.
- Collect itemized quotes from your HDB Licensed Renovation Contractor (LRC). Banks ask for the firm name and the DRC registration.
- Check your eligibility. You must be a Singapore citizen or PR, and the property must be your own HDB flat.
- Apply to the bank with the quote and your income proof. Approval often lands within days.
- Sign the letter of offer. Funds are disbursed in stages tied to reno progress, not in one lump.
- Confirm the permit window. The HDB renovation permit takes about two weeks, so apply for the loan before drawings are locked.
Time your HDB interior design Singapore loan to the permit clock
A loan disburses against milestones, and those milestones follow the permit. Hacking and drilling are allowed weekdays from 9am to 6pm, none on Sundays or public holidays, so progress is never seven days a week. Build that into your repayment view. You pay from the first disbursement, so a stalled permit is lost interest.
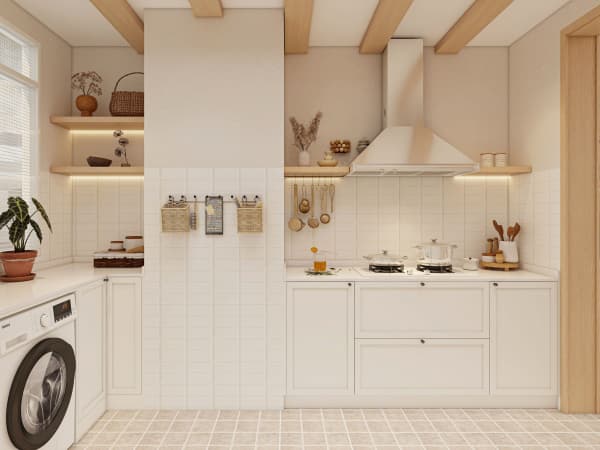
For an HDB open concept kitchen, the loan covers the approved hacking and the new carpentry, but the induction-ready setup in new BTO kitchens may shift your appliance spend. Gas stays under SP Group and SCDF rules. Keep appliance costs outside the reno loan if the bank excludes them, and fund them separately.
Spend the loan on approved items only
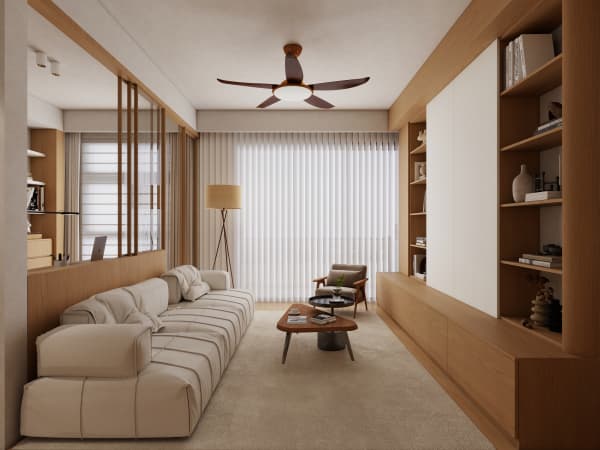
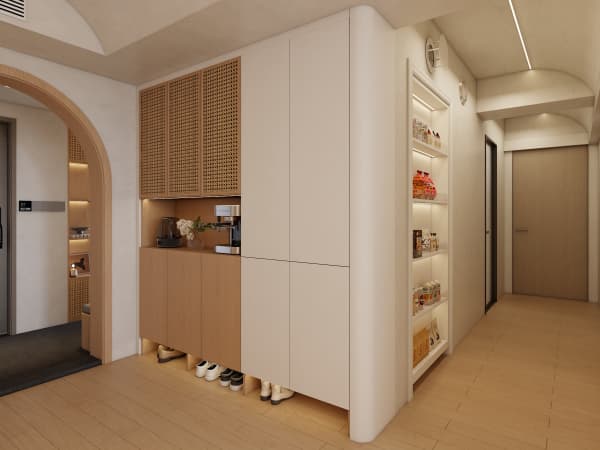
Use borrowed funds for HDB approved flooring like vinyl or laminate, laminate carpentry, and quartz countertops. These are permit-safe and durable. Skip borrowing for movable furniture you can buy later. HDB flat space saving carpentry, such as platform beds with storage and pull-out pantries, is worth funding because it is built in and adds daily value.
A reno loan works best when the whole-house customization is priced as one plan, not guessed room by room. Ask your design team for an itemized scope tied to the permit timeline. You borrow the right amount, start on schedule, and step into a finished home without draining your reserves.